

You already know that you should clean up their finances before selling your business. But do you know what needs cleaning up?
Suddenly, an expense you've always understood needs three years of supporting documentation. An overdue invoice you've been meaning to address becomes a concern about revenue quality. And the adjusted EBITDA number you had in mind looks a little different once someone else starts examining the details.
None of these issues necessarily makes your MSP a bad acquisition target. But they're much easier to address six months before due diligence than six weeks into it.
If you're considering selling your MSP, financial preparation should go beyond getting your bookkeeping up to date. You need to understand what a buyer will examine, which numbers could affect your valuation, and whether you can support the financial story you're telling.
Here's where to start.
Start with adjusted EBITDA, not just clean books
Clean financial records are important, but they're only the starting point.
A buyer wants to understand how much profit your MSP can reasonably generate under new ownership. That means looking beyond the earnings reported on your financial statements and accounting for expenses or income that may not reflect the business's normal operations.
This is where adjusted EBITDA comes in.
EBITDA stands for earnings before interest, taxes, depreciation, and amortization. Adjusted EBITDA takes that figure and makes supported adjustments to better represent the earnings a buyer might expect going forward.
In our MSP Exit Readiness Guide, the worksheet uses this formula:
Let's say your MSP reports $400,000 in EBITDA. You identify $35,000 in legitimate, documented one-time expenses, but you also received $10,000 in non-recurring income. You then determine that replacing an owner-performed role would cost an additional $45,000 annually.
Your adjusted EBITDA would be $380,000.
That number may be lower than what you initially expected, but it's also a more useful starting point for a serious valuation conversation.
And that's the difference between having clean books and being financially ready for an acquisition. Your records might be accurate enough for tax filings and day-to-day management without being organized to withstand a buyer's scrutiny.
If you're planning to sell, start calculating adjusted EBITDA well before you receive an offer.
It gives you time to investigate unusual expenses, document legitimate adjustments, and understand where your valuation assumptions might need work.
Fix your AR aging before a buyer sees it
Your MSP can report healthy revenue and still have a problem with how much of that revenue actually turns into cash.
Accounts receivable (AR) is one of the places buyers look to understand that difference.
An AR aging report shows how much customers owe and how long those balances have been outstanding. It can reveal whether your billing process is working consistently, whether certain customers are habitually late, and whether some of your reported receivables are unlikely to be collected.
Aging buckets and what buyers flag
Most AR aging reports divide outstanding invoices into five categories:
Ideally, most of your outstanding AR should be current or relatively recent.
One warning threshold identified in the MSP Exit Readiness Guide is more than 15% of total AR sitting in the 90+ day bucket.
For example, if your MSP has $200,000 in outstanding receivables and $40,000 is more than 90 days overdue, that's 20% of your total AR.
A buyer will want to understand why.
Maybe a major customer has an unresolved billing dispute. Maybe invoices have been going to the wrong contact. Or maybe nobody has consistently followed up because the finance team has been stretched thin.
The explanation is important, but so is what you've done about it.
Start by reviewing your oldest balances individually. Identify invoices that are disputed, potentially uncollectible, or simply waiting on follow-up. Resolve what you can, document what remains outstanding, and make sure your accounting records reflect realistic expectations about collectibility.
You should also track your days sales outstanding (DSO), which measures approximately how long it takes your business to collect payment after a sale.
FlexPoint's DSO Calculator can help you establish a baseline and see how changes in payment timing affect cash flow.
Concentration risk
AR aging isn't just about how old your invoices are. Buyers also want to know who owes the money.
A concentration red flag would be: your five largest clients accounting for more than 40% of total AR.
If a substantial share of your outstanding cash depends on a handful of accounts, a buyer will naturally want to understand the exposure.
Start by separating two questions: How concentrated is your overall revenue, and how concentrated are your unpaid receivables?
They aren't necessarily the same.
A large customer might account for 15% of your revenue but 30% of your AR because of slow payment habits.
Reducing concentration takes time. You may need to diversify your customer base, improve payment terms for existing accounts, or address recurring delays with particular clients.
What you shouldn't do is immediately offer your largest customer a discount just to accelerate payment. That may temporarily improve AR while reducing the value of the underlying relationship.
The objective is to make your revenue and cash flow more dependable, not simply make an aging report look better for one month.
Document your add-backs now, not during diligence
When owners calculate adjusted EBITDA, add-backs are often where things get interesting.
An add-back is an expense included in reported earnings that may reasonably be excluded when estimating the business's normalized operating performance.
The key concept here is legitimacy.
Buyers expect adjustments to be specific, supportable, and backed by documentation. Recurring operating expenses generally don't become add-backs simply because you'd prefer they weren't included.
Common categories worth reviewing include:
- Owner compensation normalization. If you pay yourself significantly more or less than the market cost of someone performing your role, an adjustment may be appropriate. But the buyer still needs to account for the cost of replacing the work you perform.
- One-time legal or consulting expenses. A genuinely unusual legal matter or a non-recurring consulting engagement may qualify, depending on its nature and whether the expense is expected to continue.
- Related-party expenses. Payments to a business owned by you or a family member may require adjustment if they aren't consistent with market rates.
- Documented, non-recurring transaction costs. Certain expenses directly associated with an unusual transaction may be considered, provided they aren't part of normal business operations.
For each proposed add-back, keep the invoice, accounting entry, explanation, and any supporting contract or correspondence together.
If you paid $20,000 for a one-time legal matter two years ago, for example, you should be able to show what the expense covered and why it isn't expected to recur.
And if you want to normalize your own compensation, document the responsibilities you perform and the likely market cost of replacing them.
A buyer may reject some proposed add-backs even when they're documented. That's part of the negotiation. Your job is to make sure every adjustment has a reasonable explanation rather than relying on a buyer to accept your preferred version of earnings.
Standardize your billing and payment follow-up process
If you're preparing your finances for a sale, it's worth examining what happens between issuing an invoice and receiving payment.
For many MSPs, that process has developed gradually. One customer pays by check, another uses a card, someone else sends ACH transfers, and a few accounts require manual reminders every month.
The process works well enough until someone tries to evaluate how consistently it works.
If this is how it works for you, try considering the cost.
As an illustrative example from our article on investing in back-office AI, an MSP processing 200 invoices a month at an average administrative cost of $12 per invoice spends:
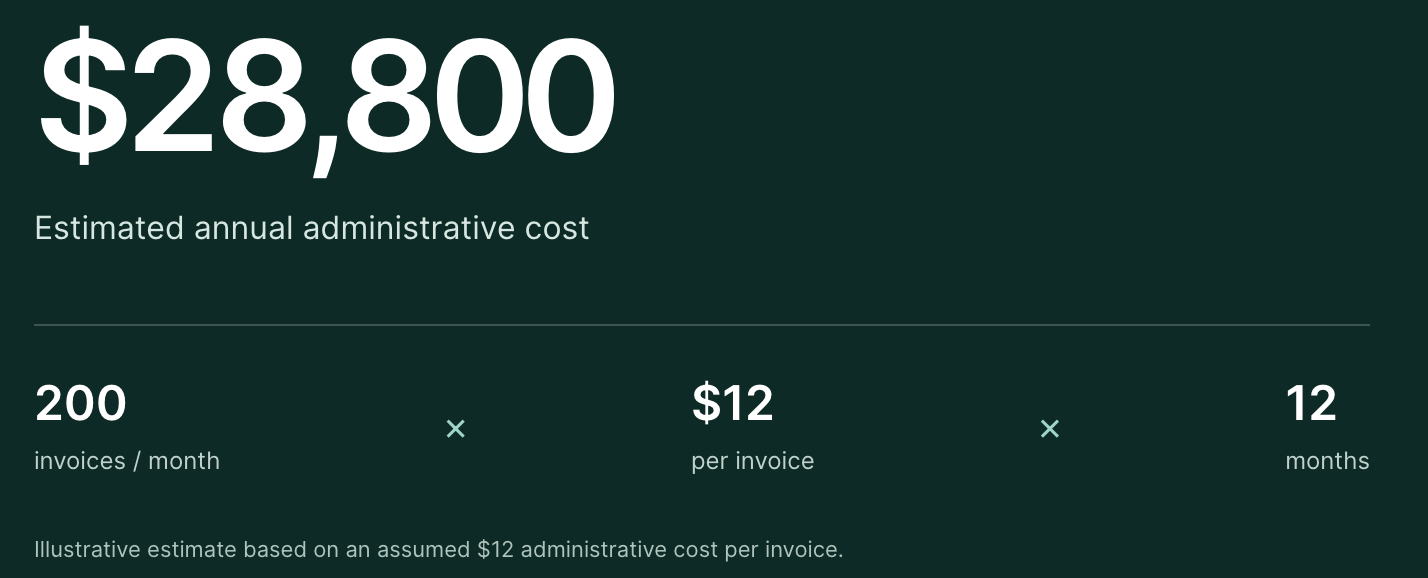
200 invoices × $12 × 12 months. This is an example, not a measured industry average or a guaranteed savings opportunity.
That's nearly $29,000 annually in administrative processing costs before considering the cash-flow impact of late payments.
You probably won't eliminate every dollar of that expense. But the example gives you a useful way to quantify the work involved and identify where better processes could reduce it.
Buyers are also interested in consistency.
If your billing coordinator has a detailed personal system for tracking overdue invoices, but nobody else knows how it works, that's a potential operational risk.
The same goes for payment reminders that happen only when someone has time, or customer billing arrangements that aren't documented anywhere.
Standardizing the process means establishing clear invoice schedules, consistent payment terms, documented follow-up rules, and reliable reconciliation between your payment platform, PSA, and accounting system.
Automation can help make that consistency easier to maintain.
For example, FlexPoint's AR Agents can take recurring AR follow-up work off your team's plate, helping ensure overdue accounts receive attention without depending entirely on someone remembering to send the next message.
And when a buyer asks how your MSP manages unpaid invoices, a documented workflow is a much stronger answer than “Sarah usually handles that.”
Separate personal and business expenses completely
This is one of the most avoidable problems an owner can bring into due diligence.
Personal expenses running through the business are a common source of disputed add-backs because they make it harder to distinguish legitimate operating costs from owner benefits.
Maybe you've used the company card for a personal trip, paid a household expense through the business, or mixed business and personal purchases on the same account.
You may know exactly which expenses are which. Your accountant may even have categorized them correctly at year-end.
But a buyer examining your records shouldn't have to take your word for it.
The fix is straightforward: use dedicated business bank accounts and credit cards for business expenses, and keep personal spending entirely separate.
If there are historical expenses that need to be reclassified, work with your accountant to correct the records and retain the supporting documentation.
As a practical minimum, aim for roughly 90 days of clean separation before beginning a sale process, while continuing to maintain that separation afterward.
Ninety days won't erase several years of mixed transactions, and buyers may review multiple years of financial history, but it gives you a starting point for demonstrating that the issue has been addressed.
Ideally, you'll make this change much earlier.
The fewer personal transactions a buyer has to untangle, the easier it becomes to evaluate your operating expenses and any legitimate owner-related adjustments.
Start building your data room now
Once your finances are in better shape, you'll need a way to share the supporting information.
That's what a data room is for.
In an acquisition, a data room is a secure, organized collection of documents that prospective buyers and their advisers can review during due diligence.
If you're wondering what happens during an MSP acquisition, this is where much of the financial preparation becomes useful. Buyers aren't simply looking at the figures you provide. They're checking the records behind them.
FlexPoint's MSP Exit Readiness Guide organizes data room preparation into seven categories:
- Financial and tax: Financial statements, tax returns, AR aging, debt schedules, and supporting financial records.
- Corporate and legal: Ownership documents, business agreements, licenses, and material legal matters.
- Operations: Documented processes, service delivery procedures, and operational reporting.
- Vendors: Important supplier contracts, software agreements, and other third-party commitments.
- Customers and revenue: Customer contracts, recurring revenue information, concentration analysis, and retention data.
- Employees: Organizational structure, employment agreements, compensation information, and key personnel responsibilities.
- Technology and security: Systems documentation, access and security policies, and relevant technology agreements.
You don't need to upload every document on day one. Start by creating the folder structure, identifying what's missing, and assigning responsibility for gathering each item.
You'll likely discover records that need updating, which is useful information to uncover now.
Keep sensitive documents access-controlled, and involve your legal and financial advisers before sharing confidential information with prospective buyers.
What financially ready looks like six months out
Six months may not be enough to resolve every issue, especially if you have significant customer concentration or several years of inconsistent financial reporting.
But it's enough time to make meaningful progress if you know where to focus.
Reiterating: here's what to have cold as an MSP owner preparing to enter a sale.
- Adjusted EBITDA: You have a working calculation that reconciles to reported financials, with explanations for each adjustment.
- AR aging: You understand your overdue balances, have a plan for older invoices, and can explain any significant concentration.
- Add-backs: Every proposed adjustment has supporting documentation and a reasonable explanation.
- Billing: Invoice schedules, payment terms, follow-up responsibilities, and reconciliation processes are documented and consistently followed.
- Expenses: Personal and business spending are fully separated, and historical exceptions have been reviewed with your accountant.
- Data room: Your core document categories are organized, and you've identified missing records before a buyer requests them.
You don't need perfection in every category.
What you need is a clear understanding of where your MSP stands, which issues could affect a transaction, and what you're doing to address them.
For a more complete assessment, The MSP Exit Readiness Guide includes a full Readiness Checklist worksheet that expands on these areas and helps you evaluate the broader financial and operational factors buyers consider.
Financial readiness starts before you decide to sell
Preparing your finances for an MSP acquisition takes more than producing a clean profit and loss statement.
A buyer needs to understand how your business earns money, how reliably it gets paid, what it costs to operate, and whether those results are likely to continue under new ownership.
The more of that work you complete before entering a sale process, the fewer surprises you'll have to explain while negotiating.
And even if you decide not to sell, your effort won't be wasted.
Better financial reporting, more consistent billing, and a clearer understanding of your earnings are useful for running the business you already own.
If you're beginning to think seriously about an exit, start with our MSP Exit Readiness Guide. It includes an adjusted EBITDA worksheet, Readiness Checklist, and other tools to help you identify what needs attention before approaching buyers.
For another perspective, review the Pre-Diligence Checklist to see the same preparation categories from a buyer's side of the table.